Wednesday, September 24, 2008

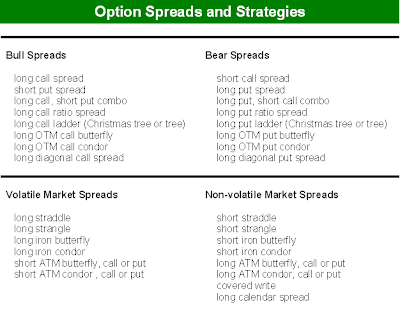
Bull Spread - Long OTM Call Condor

Image

Bullish Spread - Long OTM Call Condor

Like the Long OTM Butterfly, the Long OTM Call Condor involves 4 option positions, which means, it can be costly in terms of commissions.

The easiest way to understand this bullish spread is to view it as :

Long OTM Call Spread and Short even further OTM Call Spread

The Short position helps to fund the cost of the Long OTM Call Spread.

When to use : Mild Bullish Trend
How to establish : LONG OTM Call Spread and SHORT a higher strike Call Spread
Debit or Credit : Debit
Margin Requirement : No
What is the Maximum Profit : The distance between the LONG and SHORT Strikes (limited) - debit paid
What is the Maximum Loss : Amount paid (the debit) for the spread (limited)

Example :

Amgen (AMGN) is at $58. Long 60/62.5 Call vertical is trading at 66cents. The Short 65/67.5 Call vertical is trading at 14 cents. This Long OTM Call Condor is established with a 52 cents (66 - 14) debit.


Profit/Loss Explanation :

Debit (means you pay) for Long 60/62.5 Call Spread = 0.66
Credit (means you receive) for Short 65/67.5 Call Spread = 0.14
Total Debit = 0.52

Maximum loss = 0.52
Maximum Profit = 1.98 ( 62.5 - 60 - 0.52)
Breakeven points = 60.52 and 66.98
Profit Range = anything between the breakeven points
Probability of Success = ~25%

Risk/Reward Ratio = 0.52 / 1.98 = 0.26; ie you risk 0.26 for a profit potential of 1.00

Now, note that is a limited risk position and a limited reward one as well. The risk commensurates with the chance of success almost 1 to 1 relationship; ie 25% of success and a risk of 26cents to win $1. Very fair indeed.

Remember this is a Bullish Position, minus the risk of unlimited losses on a simple LONG AMGN stock position. The trade off is that it comes with a limited profit potential. That's trading and some say, life.

P/L Chart of AMGN Long 60/62.5/65/67.5 Call Condor


I have decidedly show the GREEKS to explain this condor.

Delta
It has a +ve 7.86 delta, which is good becos we always want a +ve delta for a bullish position, which this condor is.

Gamma
What is not good is the -ve 0.32 gamma. This is not good becos the -ve gamma will shrink the +ve delta position as AMGN price rallies. However, do note that this -ve gamma will turn positive at some time in the life of this condor position, provided AMGN rallies as desired. On the flip side, this -ve gamma will help this position from losing too much value should AMGN price drop. This is bcos the -ve gamma again will shrink the delta and with every dollar drop in AMGN, this overall condor option position will also drop lesser becos of the shrunk delta.

Theta
It has a +ve 0.09 theta, small though, but always very good becos as time passes, this condor position will gain from time decay rather than lose value, which happens for option positions that have -ve theta

Vega
It has a -ve0.21 vega, which is not necessary good. This is becos AMGN is currently at $58 and you will want the price to be somewhere between $60.52 and $66.98, which means you want AMGN price to MOVE. You want a +ve vega to help move the price of this condor position with increased volatility rather than a stationary AMGN volatility. Nevertheless, vega will change its polarity depending on what AMGN price is at.

Friday, September 12, 2008

About Rho

Rho

Rho, is the least mentioned among the greeks; delta, gamma, theta and vega.

Rho measures the impact the change in 1% risk free interest rate has on the value of the option.

In a gist, when Rho increases, the values of all Call options will increase and the values of all Put options will decrease.This occurs to every strike and expiration month options For example,

CSX : $61.61
35day 60Call : 5.10
35day 60Put : 3.40

The current risk free IR is 2%. Suppose, we increase that risk free IR by 1% to 3%, the revised Call and Put values will change. This change is caused by Rho.

35day 60Call : 5.13 (increased from 5.10)
35day 60Put : 3.37 (decreased from 3.37)

Explanation:

The reason that Calls become more expensive when IR increases, is because of "cost of carry". Remember that Call buyers have the right to exercise their Call options at any time before expiration. Supposing a trader had Long +10 6-month 55Call and is now ITM.
He could exercise this 55Call option and take delivery of CSX at $55/share but he will have to fork out $55,000 for this transaction immediately. He will still have the right to exercise his ITM Call option the next day, next week, next month or even right at the end of that 60day period. Why exercise it now, fork out $55,000 when he can deploy his $55,000 into a risk free instrument and obtain an assured interests for the next 6 months?
Of cos, if he feels that CSX will not rally any further from that juncture, he would be better just to close off this 55Call, take his profit and move on.
Hence, when risk free IR goes up, the less motivated a ITM Call option holder will be to exercise his call option. Since more people will be unwilling to do so when IR goes up, this premium is then reflected in the call option value. This is called the Cost of Carry.

Conversely, if a trader had a 60day ITM Put option, eg 60day 90Put, he will have the right to sell CSX at that strike price. Better for the trader to sell CSX at $90/share, quickly take his cash and put into a risk free instrument and earn the increased interests when holding onto those Put options earns no interest whatsoever. Hence, when Rho increases, more Put option holders will exercise their Put. Put values will drop as a consequence of increased Rho.

It would have to take a huge and sudden movement in risk free IR to have any significant impact on option values. And when such IR changes drastically, we have bigger issues to worry about.
Afterall, should the Fed Reserve Bank, decide tomorrow to raise IR from 2% to 5%, i doubt you will be rushing out to buy Call options, even when theoretically, the call values will rise.

Rho is primarily used by market makers when they hedge their positions against clients' and to price option premiums. Since they normally have very large, complex and constantly changing positions, they will take advantage of Rho to the maximum. Not so applicable for retail traders.

It is for completeness of Greek discussion, that I briefly elaborate on Rho.

About Vega

About Vega

The fifth brightest of all stars, and the third brightest in the northern sky. It will be the north polar star in about 12,000 years. In moving through the Milky Way Galaxy, the Sun is generally heading toward the position now occupied by Vega. At a distance of 7.8 parsecs (25.3 light-years, or 2.4 × 10¹⁴ km, or 1.49 × 10¹⁴ mi), Vega, or α Lyrae, is the prototypical star of spectral class A0V, indicating that it has an effective surface temperature of 9600 K (16,800°F) and derives its energy from the thermonuclear burning of hydrogen in a stable core region.

And so, Vega is really a name of a star.

But surprisingly, Vega affects option values, even when it is 25.3 light-years away. So, we best give it some attention.

Vega is an option model parameter that affects the value of an option, by the indicated amount, when Implied Volatility (IV) changes by 1%.

We will illustrate the concepts surrounding Vega by using Apple(AAPL) options. AAPL currently trades at $150.20


Sept145Call has a value of 7.20, and a vega of 0.08. The IV of this option is ~ 49%. If IV increases by 1% to 50%, this Sept145Call value will become approximately 7.28 (7.20 + 0.08). If the same call option's IV increases by 10%, thus making it 59%, then the Sept145Call will have a value of 8.00, because the vega will have increased by 10 times, from 0.08 to 0.8, as a result of 10% increase in IV.
Therefore, increasing the IV, increases the vega, which in turn increases the values of all options.
Conversely, should AAPL's volatility drop, say by 1% from 49% to 48%, that very same Sept145Call, whose original value was 7.20, now becomes 7.12 (7.20 - 0.08)
Now, you get the macro picture that IV affects option pricing via Vega (and other greeks, like Theta).

Why is Vega important?

It is important because if you were Long an option, whether a Long Call or a Long Put, you want your value of these options to go up. One way, in which these option values can increase, is by having large +ve Vegas. So that in the event, the IV increases, that large +ve Vega will also increase significantly enough to cause your option values to go up.
But, if you had WRITE Calls of Puts, you will want the value of those options you short, to decrease in value (sell high, buy low concept). One way for these options to decrease their values, is to possess -ve Vegas. In fact, when you have a NET Short position, that will automatically generate -ve Vegas.
-ve Vegas can hurt your overall portfolio, if IV spikes.

Note also that vega is smaller in the front months as compared to the further out months. This means that when IV changes, the further out months option values are more impacted because they possess larger Vegas as compared to the nearer months options.

Most traders do not to focus on Vega becos it is arguably more important to know how the IV is behaving. Afterall, what changes the vega is IV. Vega is just a resultant figure.

When IV increases all option values increase (it is so critical that it warrants repetition), for all Calls and Puts. And conversely, when IV drops, all option values drop, both Calls and Puts.

Look at the Theoretical Price (highlighted within green box)of both Calls and Puts when IV is adjusted up by 10%.


They are all higher than the "mark" value, which is the current traded value. You can easily imagine that when the IV drops by 10%, the values of all options, in each strike of each month, and every month, will decrease in value.

There is absolutely no need for AAPL share price to move 1 cent, for IV to cause option value to change drastically. This is the power of IV. So, Asian traders, the next time you buy a Call or Put warrant, remember, don't get suckered by the issuer adjusting the IV upwards. Once you buy, they turn down the IV, and without price changes to your underlying, the warrants can still lose a heck lot of value. Now, you know why warrants offered for trading in asian bourses, are ONE-sided trades, and you ain't the banker.

This is yet another reason, why you should be looking to Long options only when IV is comparatively low and Short options when IV is exceptionally high. Historical Volatility is used as a comparison. However, this is not always to be taken at face value. Some stocks' have increased volatility for extended months to years. On the flip side, some stocks which have low volatility, can remain non volatile for a good number of years as well.

Hence, you should not base your decision to go Long or Short by simply looking at Implied Volatility, although, all astute options traders will know IV of their underlying very well.

So, in summary, Implied Volatility rules...which is why no option trader will survive this game without having a very clear understanding of IV. I tell my friends that my mistress' name is Ivy. 8-)

About Theta

It's Time for Theta

Theta means Time Decay.

All options will expire one day, sooner or later. As time passes, each option will lose a little of its value due to the theta value that is attached to it. Particularly, all Long option positions value will suffer from such time decay, including weekends and public holidays, with no exception. Long options value decrease over time, because of Theta, even when the underlying stays absolutely still.

Let's review Google(GOOG), which is trading at $437.60. Its option chain is shown below.


Let me just digress a little and highlight a key ingredient; the Implied Volatility (IV) circled in green. The Sept08 options have all but 7 days to expire, the Oct options have 35 days and Dec, 98 days. Their respective Implied Volatilities :

Sept08 = 37%
Oct08 = 46%
Dec08 = 41%

Note that Oct08 has the highest IV. Please note that this is not to say that there is an error in the pricing model. The market is almost always perfectly efficient; especially when one is looking at such a liquid counter as GOOG. No one can tell the reasons for sure why the Oct's IV is higher than Dec's IV. What reasons accorded, can only be speculative, just as it speculative as to why a stock dropped 10% on a given day, without any apparent reasons. However, one can positively conclude that there exists a great deal of interests in GOOG's Oct options. The demand for these options, whether the buy or sell side, is the reason for this increased IV. It is simple economics 101. Mooncakes are most expensive becuase there is a higher demand for mooncakes during the Mooncake Festival and cheaper outside this period. Anticipated events can cause IV to increase.

However, there are always suggestions of market makers being responsible for artificially pumping up the next month's IV for all the reasons one can think of.

Now back to Theta.

Let's compare and contrast :

Within the same month, Theta exhibits this pattern

ATM options will have the highest theta assigned, as are the cases with Sept430 Call and Sept440. The reason is that, the best chances of success of any purchased options to get ITM (of cos other than those already ITM), will always be the ATM options. So, it is fair for options pricing model to allocate most premium to them, and that includes making the buyer of that ATM options, pay more for time decay. The seller of their ATM options, obviously, taking all the risks of writing, will demand a higher premium for ATM options.
Therefore, those ITM options, such as Sept400 Call, and OTM options like Sept470, will always contain comparatively lesser amounts of extrinsic value. Extrinsic value means, the additional premium an option pays for having the right to those options. With most extrinsic values attached to ATM options, correspondingly, Theta is highest always at those ATM options, both Puts and Calls.


Between Different Months, Theta Behaves in Discernable Pattern

Look at Theta for all Sept and Dec options. Across all strikes, Theta is smaller in Dec options than in Sept. For example, Sept 400 Call has a - 0.26 theta and Dec 400 Call has a - 0.18 theta. The reason that further out month has lesser theta attached to the options, is because there are many more days before those options expire.
Theta, or time decay, is experienced most when the options nears expiration. The effect is accelerated 30 days before expiration. So, in this Sept400Call, where theta is - 0.26, theoretically, ceteris paribus, theta will decay the option value by 26cents with every passing day and will decay the option value even more aggressively come closer and closer to the final expiration date.
At expiration date, all ITM, ATM and OTM options theta will revert to ZERO value. The value that time accords to these expired options, are no longer in existence. Hence, all options will lose their extrinsic value at the final second on expiration date.
In short, Theta is totally decayed at expiration date.

Now, if further out months options are supposed to have smaller theta, than why do Oct's options (being further out) have higher theta values across all similar strikes, when compared to Sept's? This is exactly opposite of what I described above.
There's no anomaly here. The only reason for Oct's options theta to be higher than Sept's is because of the markedly increased IV in the month of Oct. All that's been described about theta being highest at the ATM Oct option still applies.
But it should now be evidently clear to all that IV has a potent effect on other Greeks, including Theta. But had Oct's options IV be closer to ~39%, then those theta will likely be lower than their corresponding partners in Sept.

Increased IV will increase theta and a decreasing IV will decrease theta, everything else being constant.

This is the reason, that many traders will SELL options during HIGH Implied Volatility days and the reason why Asian traders shd NOT buy options (puts or calls) when HSI, SSE, STI do a stunning move...those warrants are very expensively priced. Since asian retail traders cannot SELL warrants, you are being forced to BUY them, if you wana trade warrants !!!! when the dust settles, and IV drops back to sane level, even if the index or stock price remain unchanged, your warrant values will drop very drastically....becos IV dropped.

Puts and Calls of Same Strike have Same Theta

There's is usually very difference in Theta figure for Calls and Puts of the similar strikes.

Theta can kill Long option traders, silently...

What About Gamma ?

Gamma

Gamma's sole purpose is to affect the Delta. It can either be friend or a foe to Delta.

As we have discussed, Delta, is the greek that determines the amount of change to the option price, when the underlying moves by a point.

Then, you will understand when Gamma is defined as the Delta's delta; ie, Gamma determines the amount of change to Delta when the underlying moves by 1 point. If delta is a the 1st derivative then the gamma is the 2nd derivative. If delta is velocity, then gamma is acceleration.

Let's look at Visa (V), currently trading at $71. The current option chains are shown below.


A Long 70Call has a delta of 0.56 and a gamma of 0.08. If V rallies up $1, then 70Call delta will change to 0.64 (0.56 + 0.08). If V drops by $1, the same option's delta will also drop to 0.48 (0.56 - 0.08).
So, it is clear that Gamma has a direct impact in the value of the option's delta. The more +ve Gamma that option position has, the bigger the movement of value option's price will swing.
This is the reason that when Long OTM Call positions are very unreactive to underlying price movement. The V example shows this.
Look at 80Call option, this is OTM Call. It has a delta of 0.04 and a corresponding gamma of 0.02. Even if V rallies from $71 to $72 now, the 80Call delta will only be increased to 0.06 (0.04 + 0.02), which translates to a 6 cents movement in 80Call value. Obviously, this OTM Sept80Call isn't worth much now; about 7.5cents and has only a 4% chance that it will become ITM by 8 days time, when this option expires.
Do you remember how we conclude that this OTM80Call has only 4% chance of getting ITM? If not, you should re-read the post on Delta.

Now for the confusing part.

Supposing you had Long V 65Call which has now a 0.82 delta and 0.04 gamma. But imagine, for some reasons, your gamma was -ve 0.10. This can happen when you have multiple option positions of the underlying, that results in a +ve delta and a -ve gamma.
If the position has a NET +ve 100 delta, supposedly, you would want the stock to rally, since a NET +ve delta is a bullish position and will be profitable only when a rally occurs. BUT, the overall gamma of this combined positions, as stated was -ve 20. Then in a 1 point rally, your delta will be reduced to +ve80 (100 - 20). This is no good. Of cos, as the stock rallies up $1, you will still make that $100 (from the initial 100 deltas), but supposing it now rallies another point, from $72 to $73, effectively, you additional profit is only $80. You will still be making money, just not as much. What is responsible for this mess up? Gamma, of cos.

Similarly, in any bearish position, where the delta is -ve, you will want to gain delta as time passes. In this case, gaining delta for a bearish position, means making the delta more "-ve"; as in -0.9 is better than -0.2. This is the tricky part; so pay attention. You will still want a +ve gamma for a -ve delta position. It is not intuitive, but it is correct notion. A +ve gamma will make a -ve delta more -ve , when the price of the underlying drops.

Another way of looking at Gamma, is to think in terms of Volatility. If you were Long or Short a position, you certainly want price action, don't you? Afterall, a stationary market will slaughter all single directional bets, like Long Call and Long Put. Hence, when you have such positions, you want Gamma to be as gigantically +ve as possible.

But, if your option strategy is for the quiet market, then you want -ve Gammas to "tame" those deltas, and even making them as small as possible..

Hence, option writers (stationary or non-volatile option positions; such as Short Strangle or Short Straddle), will want -ve gammas in their option portfolio....

If you look carefully at the option chain above, you will see that gamma is largest for ATM options. This is always the case. The reason is very simple. At expiration, all ITM Call options will have delta +1 and all OTM Call options will have 0 delta. Similarly, ITM Puts will have -1 delta and OTM Puts will have 0 delta.
Now, we are 5 minutes away from closing bell of expiration day. V is trading at 74.90, the 75Call has a good chance of being ITM and is now 0.25 delta. One second passes and V trades 75.05, this 75Call's delta immediate jumps to 0.89. See the movement of delta from 0.25 to 0.89. That huge change is caused by Gamma. Hence, all ATM options has the largest Gamma.

so, in summary, this is how these 2 GREEKs interact with Calls and Puts

.................................................Delta....................Gamma

Long Call..................................+ve...........................+ve
Short Call.................................-ve............................-ve
Long Put..................................-ve............................+ve
Short Put.................................+ve...........................-ve

Thursday, September 11, 2008

Volatility

Volatility

A word on Volatility.

A stock is said to be more volatile than others or when compared to its past , it means that its stock price has a tendency to fluctuate over a large range.

Hence, a sector ETF maybe less volatile when compared to a single stock of that same sector. This is because this ETF encompasses a wide variety of stocks. If only a small number of stocks within this ETF make huge price movement, and a great deal of others stay relatively unchanged, then the price of this ETF will not gyrate as much. It's all about statistics.

Volatility is, in fact, everything about mathematical statistics.

To understand Volatility a step further, we must introduce another statistical term, called Standard Deviation. They are a pair of Siamese twins. Speaking of one without referencing to another, is of little meaning.

Let's not talk soldiers on paper, so to speak. Let's use a real life example. Lehman Brothers (LEH)

LEH is current trading at ~$5. It was traded for ~$20 some 6 weeks ago and $65 just 9 months ago. One can consider LEH as a highly volatile stock. LEH price dropped a hefty 92% over a period of just 9 months. But exactly how volatile is this LEH and how do we quantify its volatility.

To exact how volatile a stock is, we must always look into its past price action; ie its historical price movement. Therefore, when we refer to a stock's past volatility over a period, we actually mean its Historical Volatility (HV). There's little for argument on this HV figure. Afterall, its the past and how can we argue that the price actions didn't occur.

The only debatable issue is the period in which this HV is calculated. Should the period used for calculation be 1 month, 6 months, 1 year, 5 years, or more? There's no straight answer. For a pattern trader, the shorter term HV makes more sense than to a long term investor, who might be more interested in a 3 year HV. Different periods used will show different HV, the very same reason why MA50 and MA200 are different. Therefore, one must know the period used when deriving HV.

At $5, LEH now exhibits a volatility of ~300%. This 300% is an annualized figure. What this means is that, ceteris paribus, in a year's time, LEH will have a 68% chance of trading between +300% or -300%. Now, of cos, $0, is the most that LEH can go to. But +300% means that LEH could be at $20 by then, and there's a 2/3 chance of it happening. To paraphrase, and using the Gaussian distribution (aka as Normal distribution), LEH stock price has a 68% chance of making ONE standard deviation movement in price, a 95% chance of a price movement within TWO standard deviations and a 99% chance of a THREE standard deviations movement, all in a year's time.

What if a trader wants to know the volatility other than the annualized 300% volatility? The calculation is as such:

3 month vol = 300% x 1/2 = 150% (square root of 3months /12 months = 1/2)
1 month vol = 300% x 1/3.46 = 87% (square root of 1month / 12months = 1/3.46)
1 week vol = 300% x 1/7.2 = 42% ( "" )
1 day vol = 300% x 1/16 = 18.75% ( "" )


so, with 1 day volatility at 18.75%, LEH could range between $5.93 to $4.06, all this in ONE day...

a quick check on LEH's performance today....5..30 to 3.88....now, that's pretty accurate, so far.

Delta Hedging

Delta - Revisit Again

Delta Hedging


In the above example of positions in IWM, there is a net +ve 9.65 deltas (let's just round this off to +ve 9).

This simply means that, at that juncture, if IWM rallies 1 point (meaning $1), this position will gain 9 cents or if IWM drops by $1, then this overall position will lose 9 cents.

Suffice to say that, a trader must watch the overall delta figure. If the delta of this IWM shoots up to 1000, then for every $1 movement of IWM, the portfolio will either win or lose $1000.

Now for the concept of delta hedging.

A trader may decide to hedge this above investment portfolio when the overall delta position becomes too large. Supposing, that the IWM options portfolio above went from +ve 9 delta to +ve 200 delta, which means this trader will win or lose $200 with every 1 point movement in IWM shares at that new delta figure.

Decidedly, this is too much of a risk for this trader to stomache. He can take either of these actions :

a) cut down the position size of his options, either by closing off bullish positions or adding on bearish positions, which will generate -ve deltas. as a result, this +ve 200 delta will be reduced.

b) Short IWM stocks. for every 100 shares of IWM that he shorts, he will accumulate -ve 100 delta. ONE Long share of IWM has corresponding ONE +ve delta, so ONE Short share is ONE -ve delta.

If he wants to reduce his delta overexposure by 100, then he could Short sell 100 shares of IWM. He will then bring his overall delta down to +200 from +100. This technique is known as Delta Hedging.

But delta changes all the time; it never stays static, not unless the underlying freeze in price movement.

Therefore, delta hedging is cumbersome, involves high overhead costs and is usually only practiced by professional traders/fund houses/floor traders, where the commission fees are markedly lower to non-existent.

So, the purpose of this writeup, is only to highlight that deltas change and for many reasons. In this case, deltas can change because the underlying IWM price changes. However, it is important to note that deltas can and will change, even when IWM price remains relatively unchanged. Deltas change with the passage of time and Implied Volatility.